If you already own a home, have you ever stopped to think about how much wealth you’ve built up just from being a homeowner? As home values rise, so does your net worth. And, if you’ve been in your house for a few years (or longer), there’s a good chance you’re sitting on a pile of equity — maybe even more than you realize.
What Is Home Equity?
Home equity is the difference between what your house is worth and what you owe on your mortgage. For example, if your house is worth $500,000 and you still owe $200,000 on your home loan, you have $300,000 in equity. It’s essentially the wealth you’ve built through homeownership. Right now, homeowners across the country are seeing near-record amounts of equity.
According to the Intercontinental Exchange (ICE), the average homeowner with a mortgage has $319,000 in home equity.
Why Have Homeowners Gained So Much Equity?
The rise in equity can be credited to two key factors:
1. Significant Home Price Growth
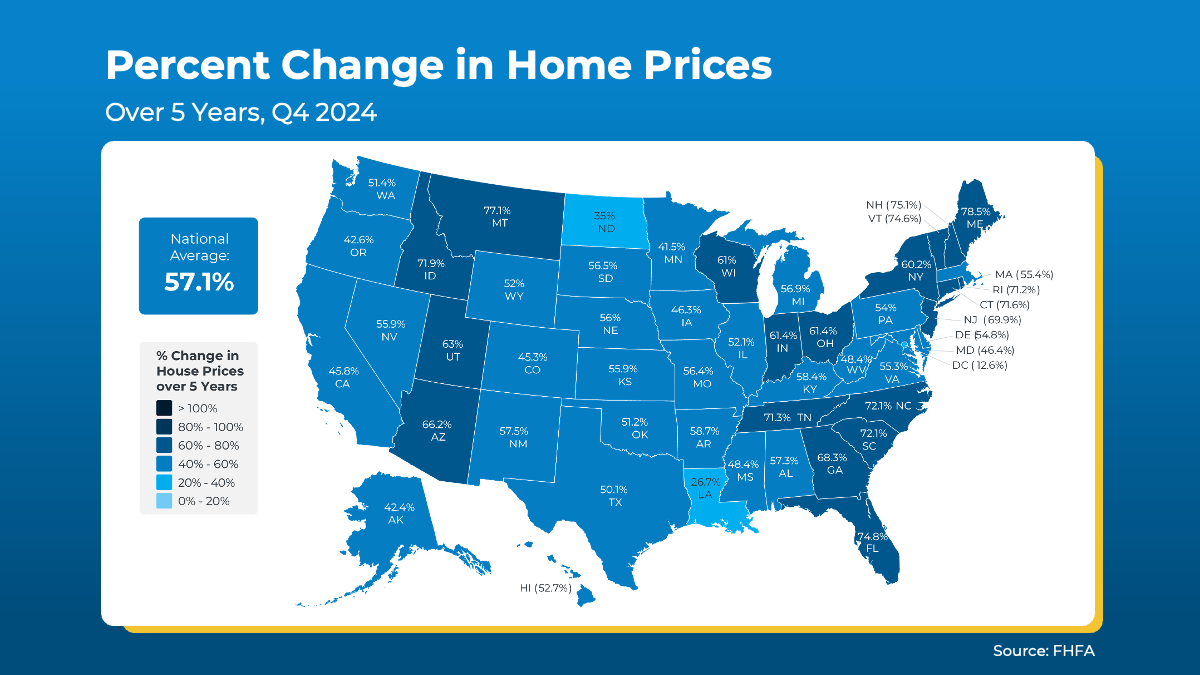
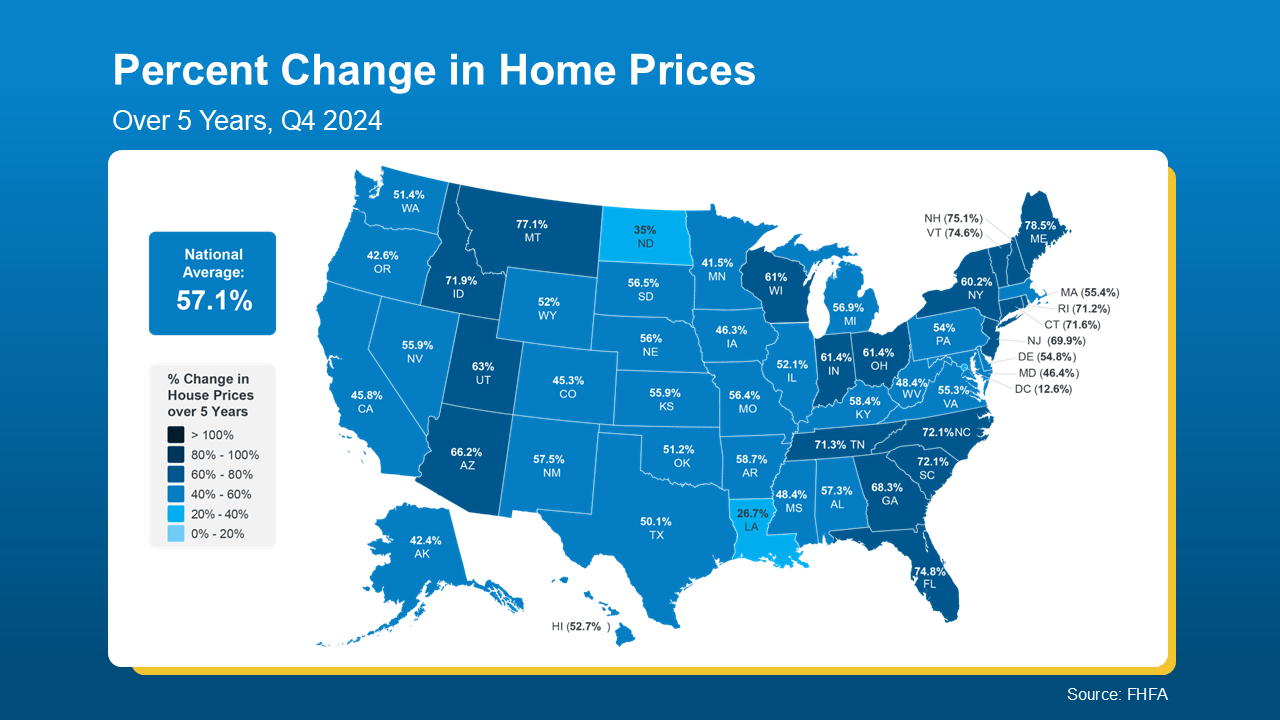
Home prices have climbed dramatically in recent years. In fact, according to the Federal Housing Finance Agency (FHFA), over the past five years, home prices nationwide have risen by 57.1% (see map below):
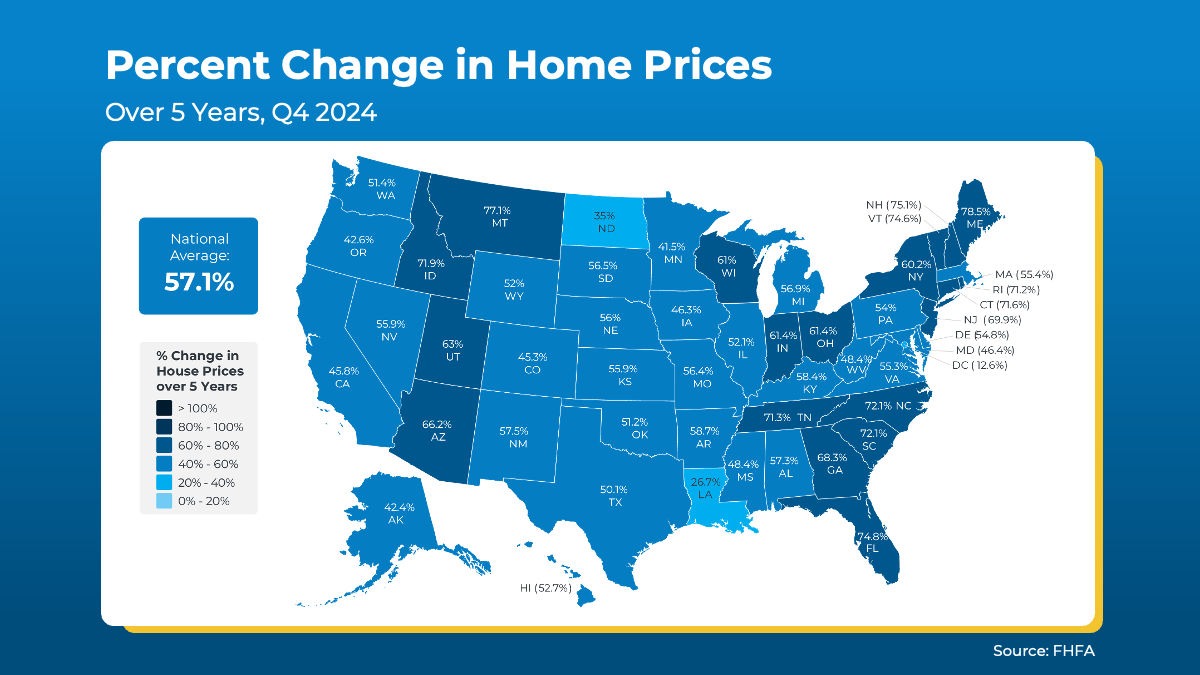 This appreciation means your house is likely worth much more now than when you first bought it.
2. Longer Tenure in Homes
Data from the National Association of Realtors (NAR) also shows people are staying in their homes longer than they used to, with the average tenure now being close to 10 years (see graph below):
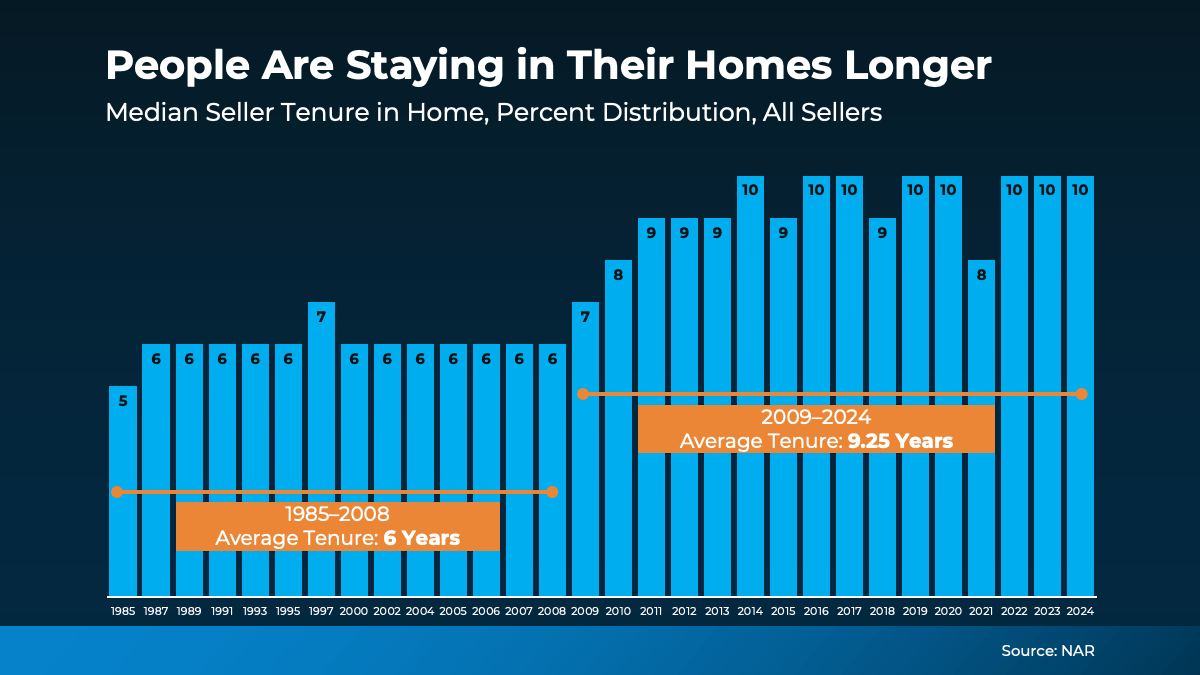 This increase means homeowners are benefiting even more from home values growing over time as they’re paying down their mortgages. That’s because the longer someone lives in their house, the more that home value grows, which directly increases equity.
And if you’re one of those people who’s been in their home for 10 years or more, know this – according to NAR:
“Over the past decade, the typical homeowner has accumulated $201,600 in wealth solely from price appreciation.”
The Benefits of Having Home Equity
What does this mean for you? Your house might be your biggest financial asset – and it could open some exciting opportunities for your future. Let’s break it down.
Moving to Your Next Home
Your equity could help you cover the down payment for your next home. In some cases, it might even mean you can buy your next house in all cash, especially if you’re looking to downsize or move to a less expensive area.
Financing Home Improvements
Thinking about upgrading your kitchen, adding a garage, or tackling other key projects? If you do it right, your equity can provide the funds to make those improvements happen, increasing the value of your home and making it more enjoyable to live in, too.
Starting a Business
If you’ve been dreaming about starting your own business, your equity could be the kickstart you need to make it happen. Whether it’s for startup costs, equipment, or marketing, leveraging your home’s value can help bring your entrepreneurial goals to life while driving your long-term earning potential forward.
Fueling Your Retirement
Your home equity could be the key to funding your next chapter, too. By downsizing or moving to a more affordable area, you can unlock cash to support your retirement goals or invest in the lifestyle you’ve been hoping for – all while simplifying your living situation.
Bottom Line
Whether you’re thinking about selling, upgrading, or simply want to understand your options, your home equity is a powerful resource – and your trusted RE/MAX® agent can help you understand exactly what you’re working with.
Want to find out how much your home is worth? Send me a quick reply, and I’ll do a professional assessment for you. The real number may surprise you.
 But remember, rate projections will continue to shift as new information becomes available. Expert forecasts are based on what they know right now. If there’s increasing uncertainty around inflation, employment, government policies, or other key economic drivers, mortgage rates will move. So, don’t get caught up in the exact numbers or try to time the market. Instead, focus on the fact that a bit more stability in rates isn’t a bad thing – and even a small change can help your bottom line.
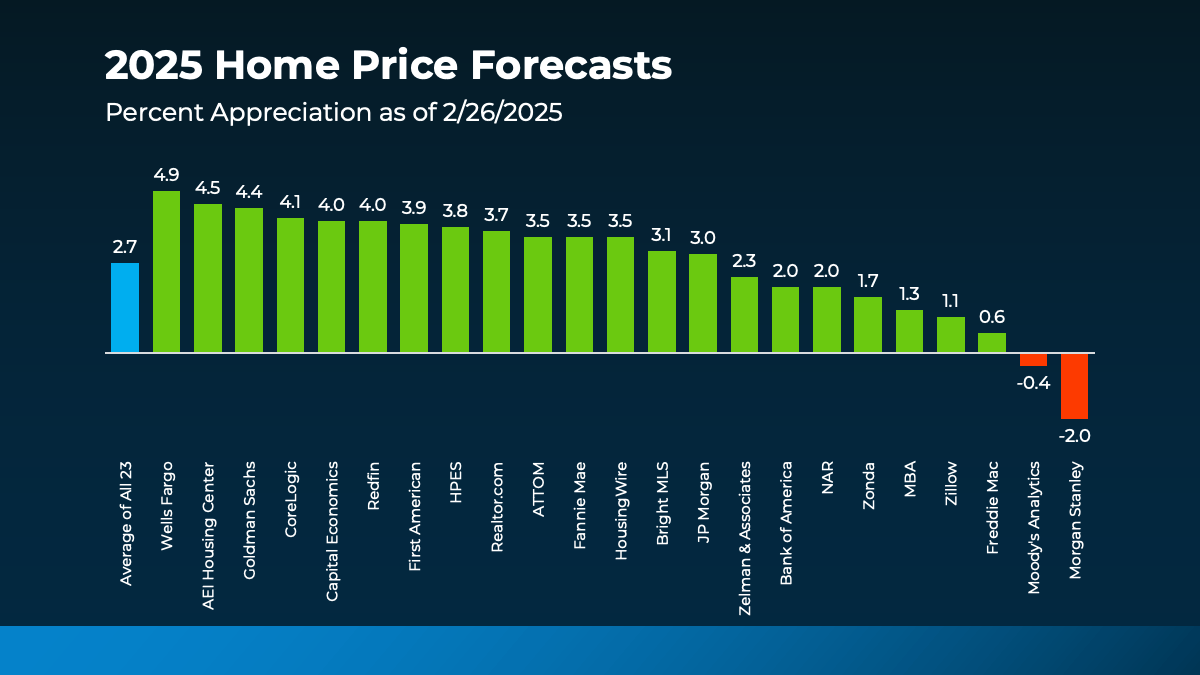 So, don’t expect a sudden drop that’ll score you a big deal if you’re thinking of buying this year. While that may sound disappointing if you’re hoping prices will come down, refocus on this. It means you won’t have to deal with the steep increases the market felt in recent years, and you’ll also likely see any home you do buy go up in value after you get the keys in hand. And that’s a good thing.
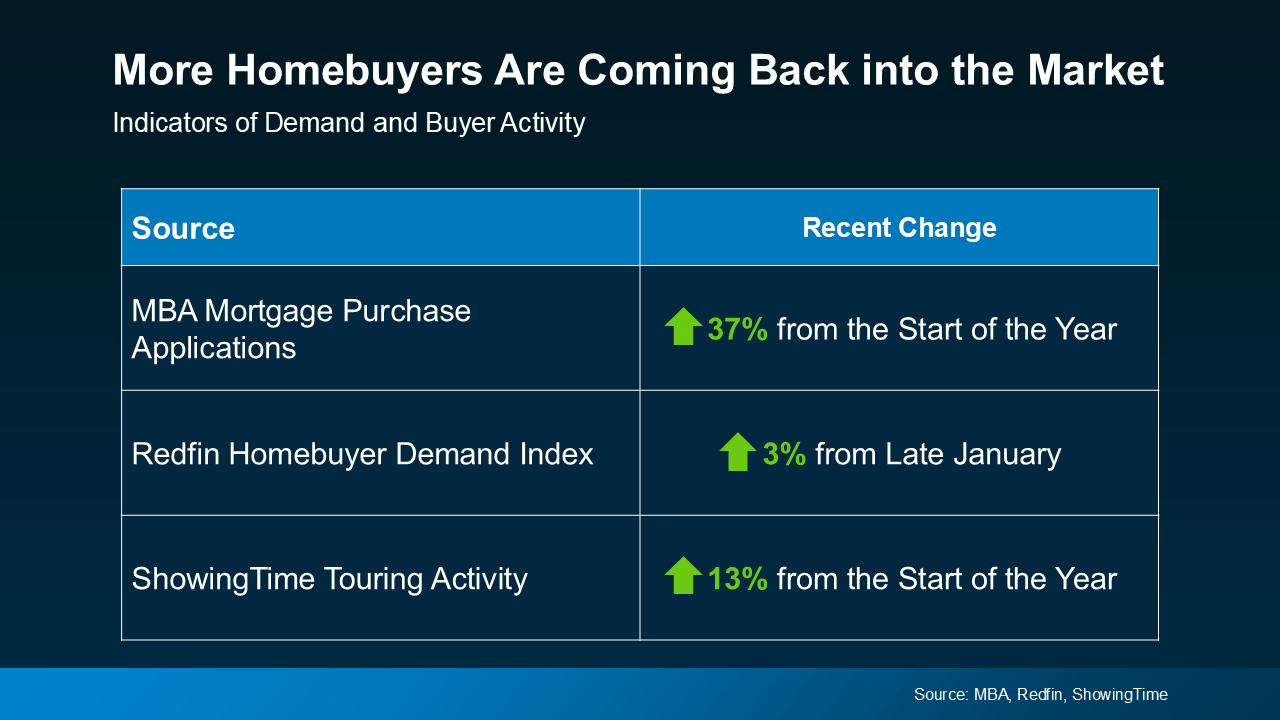
 If you’ve been holding off on selling because you were worried about buying your next home at today’s rates and prices, let that sink in. It may be more than enough to help close the affordability gap and get you into your next house.
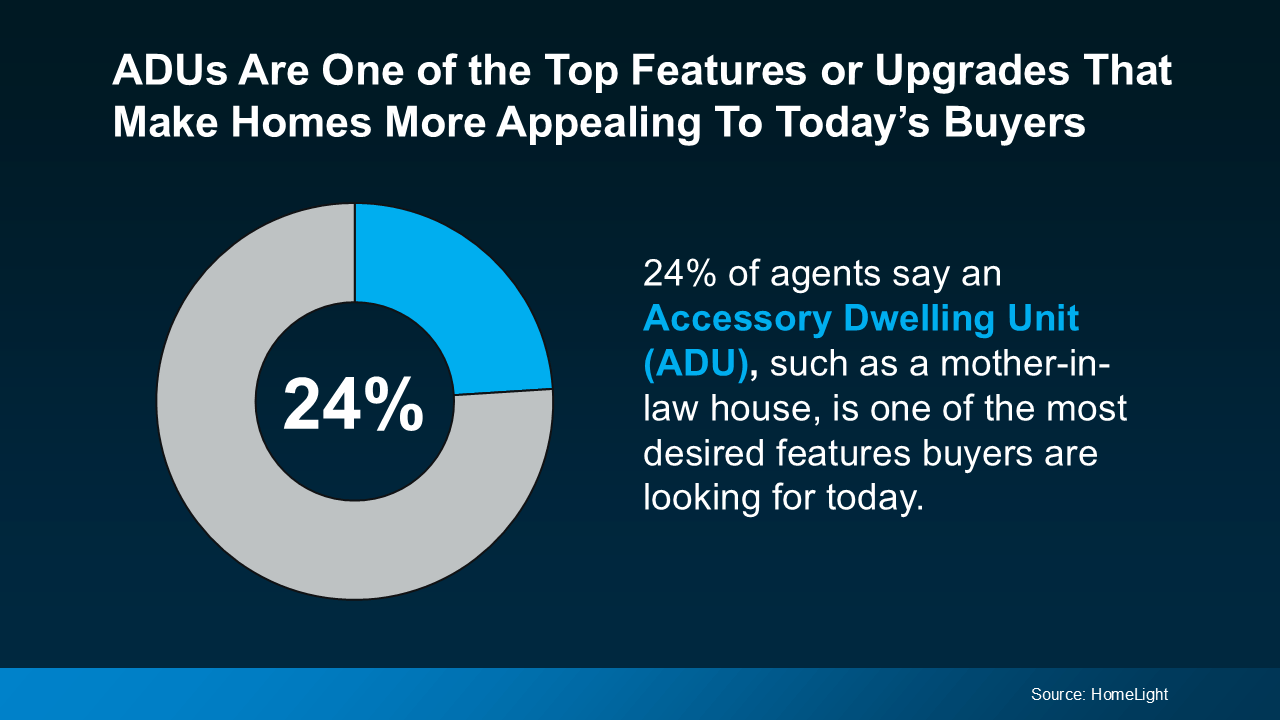 The growing appeal makes sense. With rising costs all around you, an ADU can help supplement your income and ease some of the strain on your wallet. Whether you buy a home that has one already or you add one on, it gives you the option to rent out that portion of your home to help pay your mortgage.
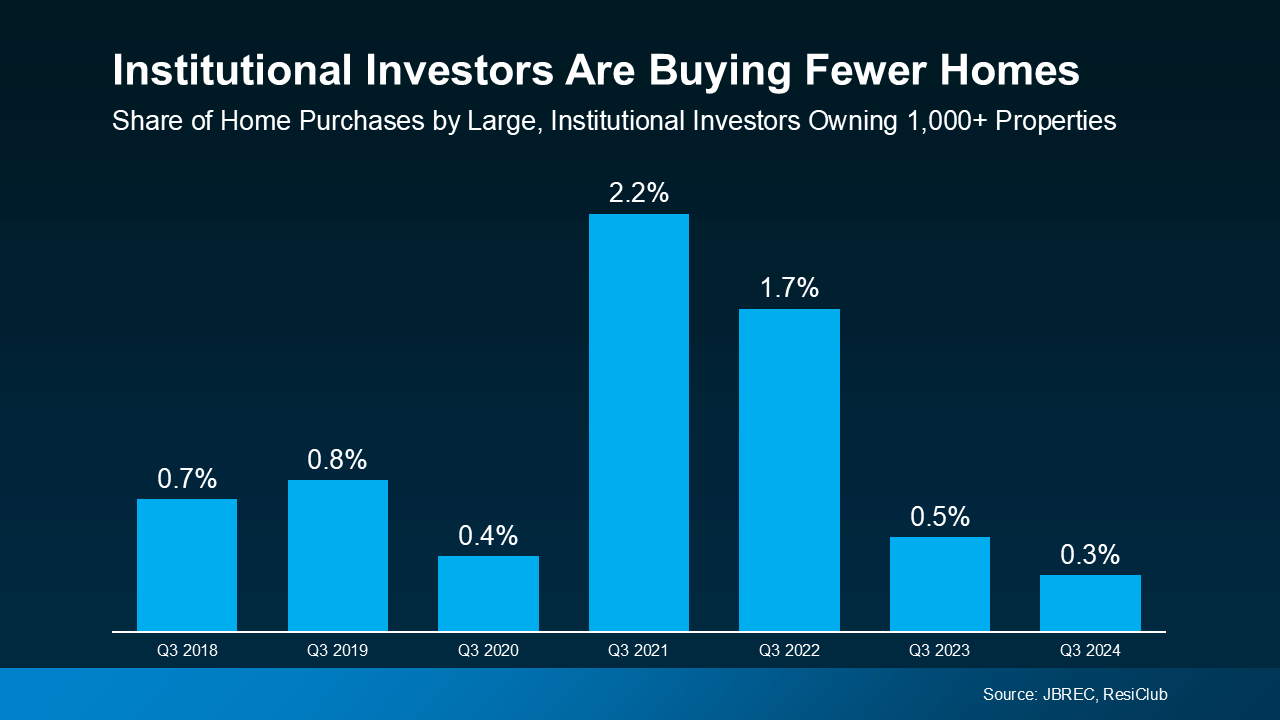 That’s a major shift, and it means far fewer investors are competing in the market now than just a few years ago.
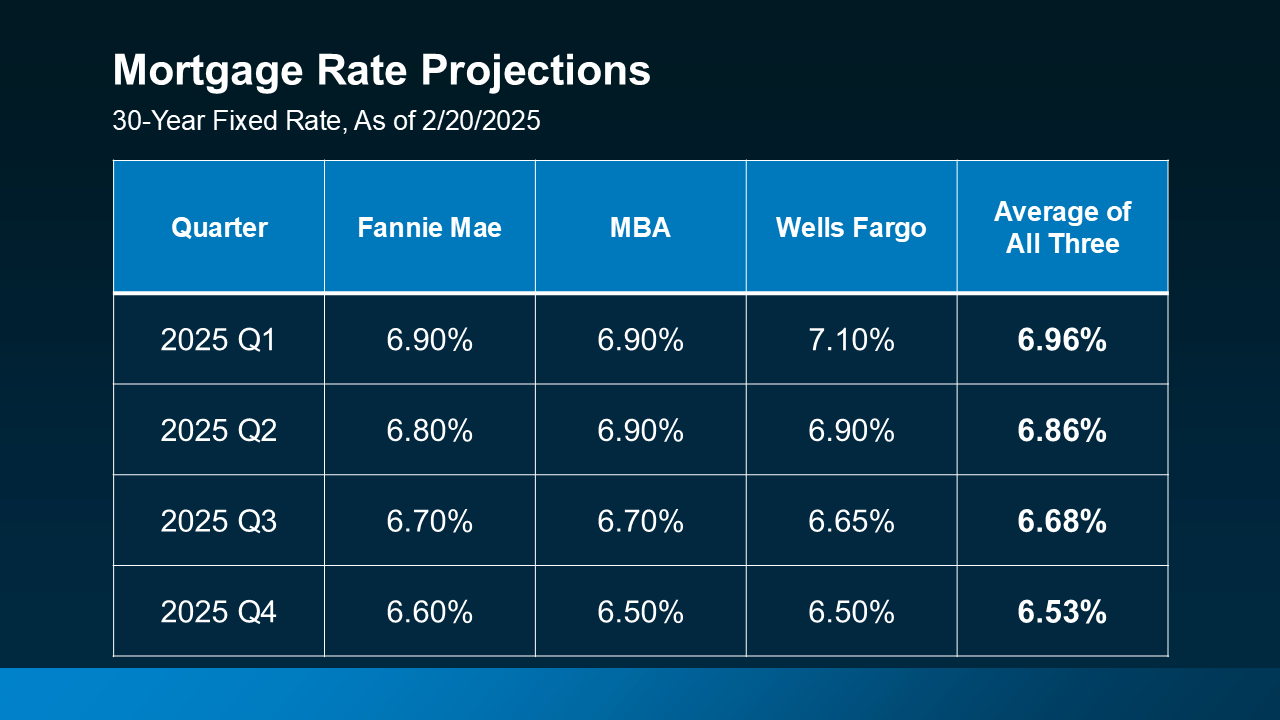 That means if you’re holding off on buying a home in hopes of much lower mortgage rates, you may be waiting a while. And if you need to move because something in your life has changed, like a new job, a new baby, or a marriage – waiting that long may not be an option.